SIPP vs Workplace Pension: Which Grows Your Retirement Faster?
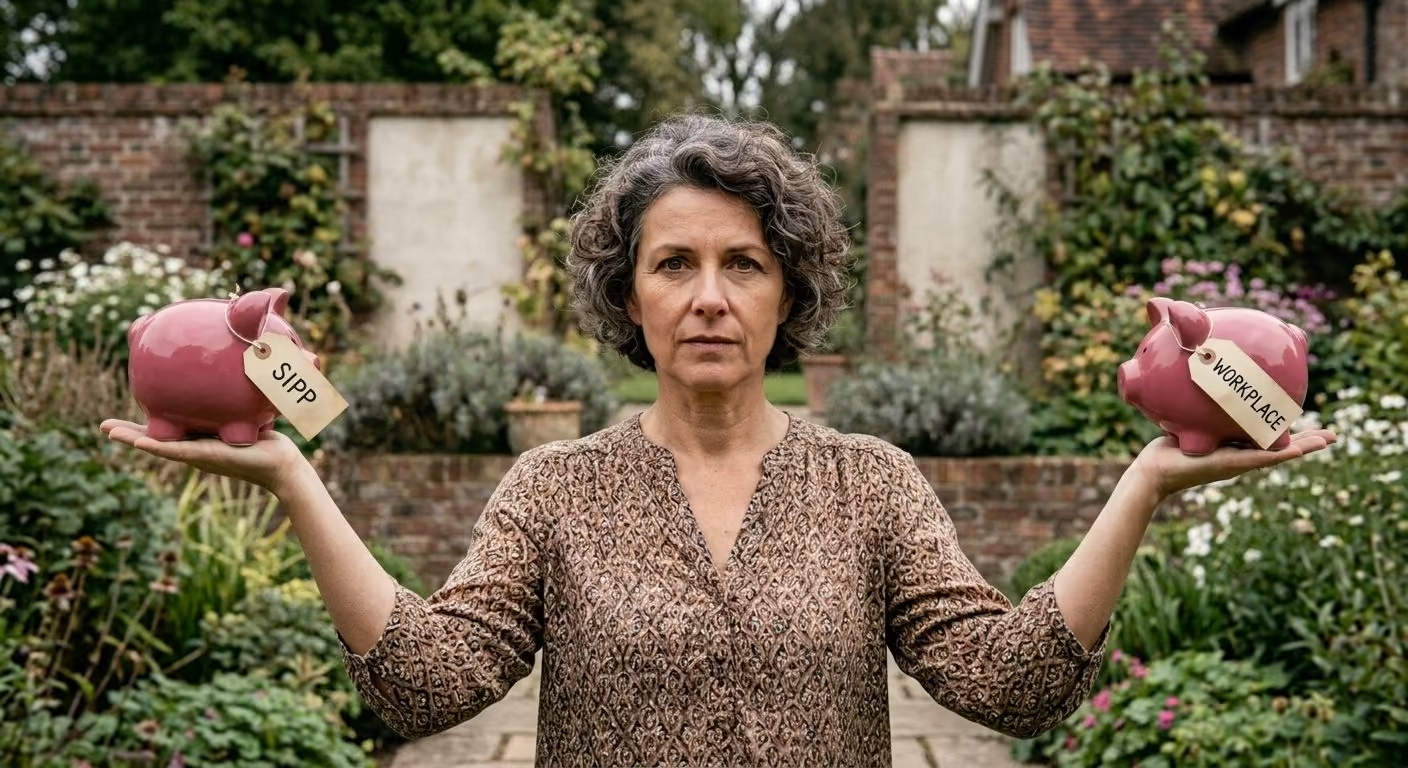
A SIPP gives you full control. A workplace pension gives you guaranteed employer money. Here's the honest comparison — and why most people shouldn't be choosing between them at all.
Disclaimer: This article is for informational and educational purposes only and does not constitute financial or tax advice. Figures are based on publicly available data as of 2026 and are illustrative — always check your own scheme documentation and current thresholds before making decisions.
Key Takeaways
A SIPP (Self-Invested Personal Pension) gives you full control over what you invest in and how much you pay in — but it has no built-in employer contribution unless your employer chooses to pay into it directly
A workplace pension comes with a guaranteed minimum employer contribution (at least 3% of qualifying earnings) — money a SIPP simply can't replicate on its own
Both get the same tax relief on contributions — a basic-rate taxpayer's £80 becomes £100 in either account automatically
Fees work differently: workplace schemes often negotiate lower bulk fees on your behalf, while SIPP fees vary widely by provider and fund choice — sometimes cheaper, sometimes not
For most employees, the honest answer isn't "either/or" — it's keep the workplace pension for the match, and use a SIPP to consolidate old pots or add extra control
If you're self-employed or your employer doesn't offer a scheme, a SIPP is usually your only realistic route to pension tax relief
At a Glance — SIPP vs Workplace Pension
SIPP
Workplace Pension
Employer contribution
None, unless your employer chooses to pay in directly
Guaranteed minimum — at least 3% of qualifying earnings
Investment choice
Wide — individual shares, ETFs, investment trusts, thousands of funds
Usually limited to the scheme's fund range, often a default "lifestyle" fund
7 min read·September 24, 2026·3
Serena Voss
Retirement & Personal Finance Strategist
Fees
Vary by provider — platform fee plus fund fees, sometimes very low
Often lower per-member due to employer bulk-negotiating, admin sometimes employer-paid
Contribution flexibility
Fully flexible — pay in any amount, any time
Fixed % via payroll, though you can usually increase it
Yes — via relief at source or net pay arrangement, depending on the scheme
Who sets it up
You, with a provider of your choice
Your employer, automatically
Earliest access
Age 55, rising to 57 from 2028
Age 55, rising to 57 from 2028
Neither is objectively "better." A SIPP is a wrapper you control; a workplace pension is a wrapper that comes with free money attached. The right mix depends on your employment status, how much you value control, and whether you're already capturing everything your employer offers.
What's Actually Different Between Them?
A workplace pension is set up automatically by your employer under auto-enrolment rules. You don't choose the provider, and your investment choices are usually limited to a shortlist the scheme offers — typically a sensible default fund that gradually shifts from higher-risk to lower-risk as you approach retirement. Its biggest advantage isn't the investment range — it's the employer contribution, which only exists because you're enrolled in that specific scheme.
A SIPP is a personal pension you open yourself, with any provider you choose. You pick the investments — from simple low-cost index funds to individual shares — and you control exactly how much goes in and when. Nobody tops it up automatically unless you arrange it, which means the growth you get is a function of your own contributions, tax relief, and investment returns, without a guaranteed employer boost sitting underneath it.
MoneyHelper's guide to SIPPs is a solid, independent starting point if you're weighing up opening one for the first time — it covers eligibility, typical costs, and how SIPPs compare to other personal pension types in plain English.
Why "Which Grows Faster" Almost Always Comes Down to One Thing
Strip away the fund choice, the fees, and the branding, and the honest answer to "which grows your retirement faster" comes down to a single question: does an employer contribute to it?
If the answer is yes — which it is for any active workplace pension — that scheme has an almost insurmountable head start. An employer paying in an extra 3%, 5%, or more of your qualifying earnings is adding money that a standalone SIPP has no equivalent for, unless you're self-employed and paying employer contributions into your own SIPP through a limited company (more on that below).
Where a SIPP tends to pull ahead is on fees and flexibility over the very long run — a well-chosen, low-cost SIPP can outperform a workplace scheme sitting in an expensive, sluggish default fund, purely on cost drag compounded over decades. But that's a fee argument, not a "SIPP beats employer money" argument. Free money is difficult to out-invest your way past.
Want to see exactly how much difference an employer match makes over 20–30 years? Model both scenarios in our Retirement Calculator.
Worked Example: £300 a Month, Two Ways
Workplace Pension (with employer match)
Standalone SIPP (employee only)
You contribute
£300
£300
Tax relief added
£75 (to £375)
£75 (to £375)
Employer contribution (assume matched)
£300
£0
Total invested monthly
£675
£375
Investment control
Limited to scheme's fund range
Full choice of funds and platforms
Typical annual fee
0.30–0.75%, often employer-subsidised
0.20–0.45%, fully self-selected
Illustrative only — assumes a generous 1:1 employer match up to £300 and basic-rate tax relief; actual employer matching varies significantly by employer.
In this example, the workplace pension puts nearly double the money to work each month — a gap that lower SIPP fees, even compounded over 30 years, would struggle to fully close. That's why, for most employees, the workplace pension isn't a "which one" decision at all — it's the base layer you build on top of.
When a SIPP Genuinely Makes More Sense
There are specific situations where a SIPP isn't just a nice-to-have — it's the more sensible primary vehicle:
You're self-employed or a contractor. Without an employer, there's no workplace pension to auto-enrol into. A SIPP is typically your most tax-efficient route to retirement saving, and if you run your own limited company, employer contributions paid directly from the company can be treated as an allowable business expense — a meaningful tax advantage worth discussing with an accountant.
You want to consolidate old pension pots. If you've had several employers, you may have several small workplace pensions scattered across old providers. Transferring them into a single SIPP can make them easier to track and manage — though always check for exit fees or the loss of valuable guarantees (like a guaranteed annuity rate) before transferring anything.
You've already maxed out your employer match and want more control. Once you're capturing the full employer contribution available to you, additional pension saving can reasonably go into a SIPP if you specifically want a wider investment choice than your workplace scheme offers.
Your workplace scheme has genuinely high fees or a poor fund range. This is less common than it used to be, but it does happen — if your default fund has consistently high charges and limited alternatives, a SIPP for additional voluntary contributions can be the more cost-effective option.
Fees — Where the Comparison Gets Less Obvious
It's tempting to assume workplace pensions are always cheaper because of employer bargaining power, or that SIPPs are always cheaper because of low-cost platform competition. Neither assumption reliably holds.
Large employer schemes with a big membership base can often negotiate annual charges well below 0.5%, sometimes with the employer covering some or all of the admin cost directly. Smaller employer schemes, or older "legacy" workplace pensions, can carry charges above 1% — genuinely expensive by modern standards, and worth checking rather than assuming.
On the SIPP side, low-cost providers can charge as little as 0.20–0.45% in platform and fund fees combined for a simple index-fund-based portfolio — but a SIPP built around actively managed funds or frequent trading can end up considerably more expensive than a well-run workplace scheme.
The only way to know which is actually cheaper for you is to check your own workplace scheme's annual charge against a SIPP provider's fee schedule directly — never assume based on the type of account alone. Whichever SIPP provider you're considering, it's worth a quick check on the FCA register to confirm it's properly authorised before transferring or contributing any money.
Curious what a 0.3–0.5% fee gap is actually worth over decades? Run the comparison through our Investment Calculator.
Common Mistakes
Opening a SIPP and reducing workplace pension contributions below the employer match threshold — trading guaranteed free money for extra control is rarely a good trade
Assuming a SIPP is automatically cheaper without actually comparing the annual charges against the current workplace scheme
Transferring an old workplace pension into a SIPP without checking for exit fees or lost guarantees, particularly on older "defined benefit" or guaranteed-annuity-rate schemes, which can be extremely valuable to give up
Leaving old workplace pensions untouched and untracked instead of either consolidating them into a SIPP or at least confirming their current value and fund choices
Treating "which grows faster" as purely an investment-performance question, when the employer contribution is usually the single biggest factor in the entire comparison
What You Should Do Right Now
Confirm you're capturing your full employer match. If you're not contributing enough to get 100% of what your employer offers, fix that before considering a SIPP at all.
Check your workplace scheme's annual charge. Compare it honestly against a low-cost SIPP provider's fees for a similar fund mix.
Locate any old workplace pensions. Decide whether to leave them, transfer them into your current scheme, or consolidate them into a SIPP — checking for exit penalties or lost guarantees first.
If you're self-employed, open a SIPP without delay. Tax relief on contributions is available regardless of employment status, and there's no equivalent auto-enrolment safety net doing it for you.
Model both paths for your own numbers. Use our Retirement Calculator to compare your current workplace pension trajectory against a SIPP-based alternative.
For the large majority of employed people, this isn't really a competition. A workplace pension with an employer match will almost always grow faster than a standalone SIPP, because free, guaranteed employer money is a head start that investment choice and lower fees rarely close on their own.
Where a SIPP earns its place is everywhere the workplace pension doesn't reach: self-employment, consolidating old pots, and adding extra control once the employer match is already fully captured. Used together — workplace pension for the match, SIPP for flexibility and consolidation — most people end up with a stronger, more efficiently managed retirement pot than either account could build alone.
Both are protected up to £85,000 per person, per firm, under the Financial Services Compensation Scheme if the provider itself fails — so the real decision here is about growth and control, not safety.
Frequently Asked Questions
Can I have a SIPP and a workplace pension at the same time?
Yes. Most people who use a SIPP do so alongside an active workplace pension, not instead of one. There's no restriction on holding both, and combined contributions simply count toward your overall annual pension allowance.
Does a SIPP get the same tax relief as a workplace pension?
Yes. Both receive automatic basic-rate tax relief, and higher and additional-rate taxpayers can claim further relief via Self Assessment in either case. Gov.uk's guidance on pension tax relief explains exactly how the relief is calculated for each tax band.
Should I transfer my workplace pension into a SIPP?
Only after checking carefully — some older workplace pensions carry valuable guarantees (like guaranteed annuity rates) or may charge exit fees that outweigh any benefit of moving. For a current, active workplace pension with an ongoing employer match, transferring out isn't usually advisable, since you'd lose future employer contributions from that scheme.
Is a SIPP riskier than a workplace pension?
Not inherently — the risk depends entirely on what you invest in, not which wrapper holds it. A SIPP invested in a diversified, low-cost fund carries broadly similar market risk to a typical workplace pension default fund; a SIPP concentrated in a handful of individual stocks carries considerably more.
What if my employer doesn't offer a pension at all?
By law, eligible employees must be auto-enrolled into some form of workplace pension, so this is uncommon for employees. If you're self-employed or a contractor without access to one, a SIPP is generally your primary route to pension tax relief.
This article is for informational and educational purposes only and does not constitute financial or tax advice. Figures are illustrative and based on publicly available data from GOV.UK, MoneyHelper, and the FSCS as of 2026. Please check your own scheme details and seek regulated financial advice before transferring or consolidating any pension.
Still with us?
Take the community poll, test yourself with the quiz — or both.
Topic hubs
Browse more articles in these categories and tags.
Serena Voss is an Investing, Wealth, and Personal Finance strategist with a passion for making complex financial concepts accessible to everyday people. She specialises in goal-based financial planning, behavioural economics, and helping readers translate financial knowledge into confident, consistent action.
125K followers89 articles
Related reading
Related articles
Closely related by shared tags and categories — continue in this topic cluster.