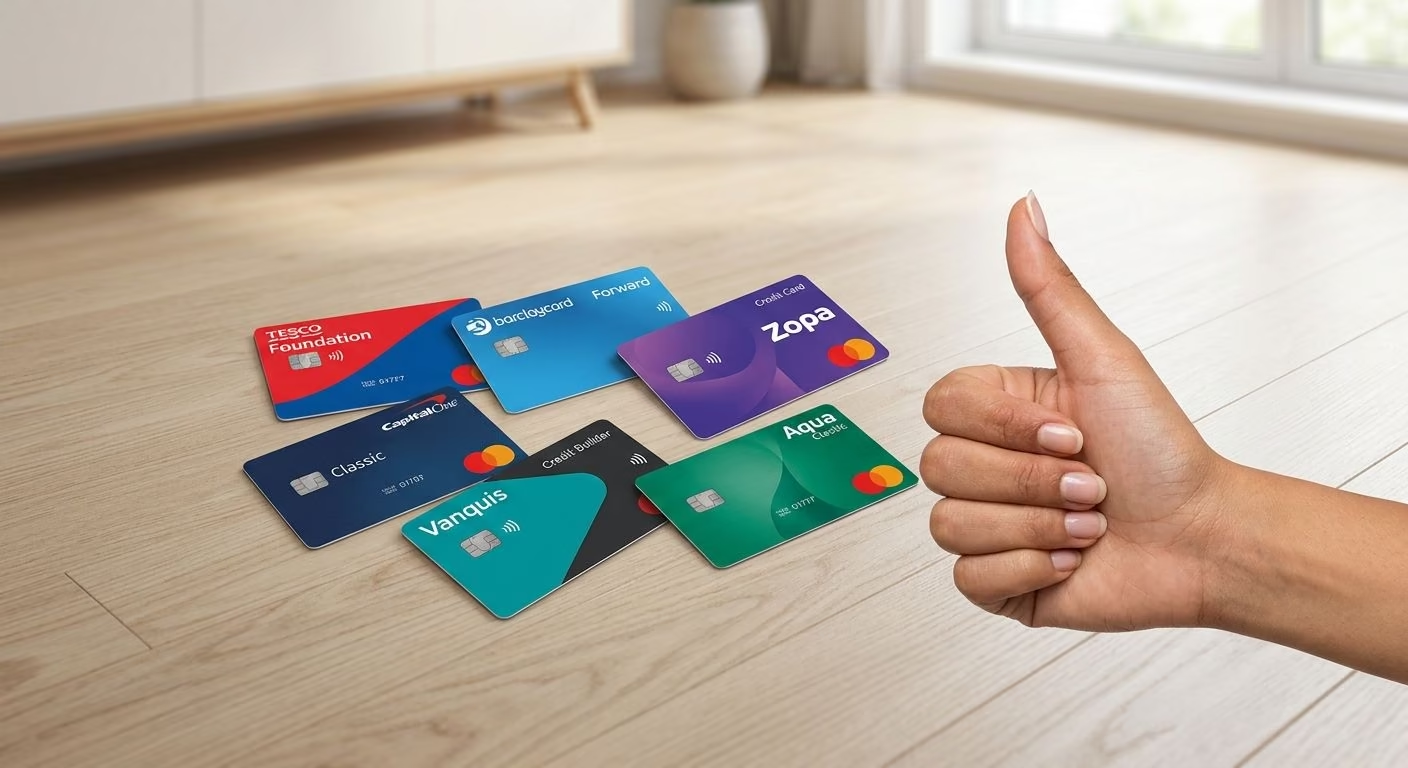
Six UK credit builder cards compared on rate, limit and features, from Tesco Foundation's 29.9% APR to Aqua for poor credit. Find the right card for your situation and learn how to use it to build your score.
Note: Rates and limits below were checked on providers' websites in September 2026 and can change at any time. Representative APRs are what at least 51% of accepted applicants get. Your rate and limit depend on your circumstances. This article is for educational purposes and isn't financial advice.
Key Takeaways
A credit builder card is a normal credit card with a low starting limit and easier approval, designed for people with a thin or damaged credit file
Representative APRs on the cards we compared range from 29.9% to 39.9%, so the interest rate only matters if you carry a balance. Paying in full every month makes any of them free to use
Tesco Foundation has the lowest representative rate (29.9%). Barclaycard Forward cuts your rate if you pay on time. Capital One Classic offers the highest limit ceiling at £4,000
Always use each provider's eligibility checker first. It's a soft search, so it won't affect your score
Use one card for one small, regular bill, and you can see a real difference in 6–12 months
At a Glance: Credit Builder Cards Compared
Card
Representative APR
Credit limit
Stand-out feature
Tesco Foundation
29.9% variable
£200–£1,500
Lowest rate, plus Clubcard points
Barclaycard Forward
33.9% variable
£50–£1,200
Rate cut for paying on time
Zopa Credit Card
34.8% variable
Personalised
No fees abroad, app-first
Capital One Classic
34.9% variable
£200–£4,000
Up to 2 limit increases a year
7 min read·September 27, 2026·0
Maya Thornton
Writer
Vanquis Credit Builder
37.9% variable
£250–£2,500
Cashback with selected retailers
Aqua Classic
39.9% variable
£250–£1,500
Built for poor or no credit history
How Credit Builder Cards Work
Lenders need evidence that you can handle credit. If you have no history, for example because you're young, new to the UK or have always used a debit card, they have nothing to go on. If you have bad history, such as missed payments or a default, they see extra risk.
Credit builder cards solve this by lending small amounts at high rates. The high rate protects the lender. The low limit protects you. Every month, your payments are reported to the credit reference agencies. After six to twelve months of on-time payments, you have the recent track record that mainstream lenders want to see.
The key point is this: the APR only costs you anything if you don't clear the balance. Set up a direct debit for the full statement balance, and you'll pay no interest at all.
The Cards Reviewed
1. Tesco Foundation: Best for the Lowest Rate
At 29.9% representative APR, the Tesco Bank Foundation card has the lowest rate on our list. Limits run from £200 to £1,500. It's also the only card here that earns rewards: 1 Clubcard point for every £4 spent at Tesco and every £8 spent elsewhere.
Watch out for: the rewards are modest. Pick this card for the rate, not the points.
Best for: anyone who might occasionally carry a small balance, and regular Tesco shoppers.
2. Barclaycard Forward: Best for Rewarding Good Behaviour
The Barclaycard Forward starts at 33.9% representative APR. Its "price promise" reduces your rate by 3% if you make every payment on time in the first year, and by a further 2% in the second. New customers also get 0% on purchases and balance transfers for 6 months. Balance transfers carry a 2.9% fee.
Watch out for: limits can start as low as £50. You also need some credit history, so a completely empty file may be declined.
Best for: young adults building from scratch who want a big-bank card and a lower rate over time.
3. Zopa Credit Card: Best App Experience
Zopa's card has a representative APR of 34.8%, with rates from 29.8%. There are no fees for spending abroad. You can view your PIN, set up automatic repayments and use "Credit Cushion" to set aside part of your limit for planned spending, all in the app.
Watch out for: it's app-only, with no branches.
Best for: people who manage their money on their phone and travel occasionally.
4. Capital One Classic: Best for Room to Grow
The Capital One Classic has a 34.9% representative APR and starting limits from £200 to £4,000, the widest range on this list. Capital One reviews accounts for up to two credit limit increases a year, so your limit can grow as your history does.
Watch out for: it's a plain card with no rewards and no introductory 0% period.
Best for: anyone who expects to need a bigger limit later but wants to start carefully.
5. Vanquis Credit Builder: Best for Cashback
Vanquis has won Moneyfacts' Credit Builder Card Provider of the Year three years running. Its Credit Builder card has a 37.9% representative APR and limits of £250 to £2,500, plus cashback with selected retailers.
Watch out for: the rate is at the high end. Carrying a balance on this card gets expensive fast.
Best for: people with a poor history who will pay in full every month.
6. Aqua Classic: Best for Poor or No Credit History
Aqua is aimed squarely at people other lenders may turn down. The Aqua Classic has a 39.9% representative APR and limits of £250 to £1,500. Its SafeCheck eligibility tool doesn't affect your score, and the Aqua Coach app includes free credit score tracking.
Watch out for: it has the highest rate on this list, so treat it strictly as a card you pay off in full.
Best for: people with past defaults or very thin files who have been declined elsewhere.
Which Card Should You Choose?
Your situation
Start with
No history, aged 18–25
Barclaycard Forward or Capital One Classic
Might carry a small balance now and then
Tesco Foundation
Past missed payments or a default
Vanquis or Aqua Classic
Travel abroad sometimes
Zopa
Declined elsewhere
Aqua Classic, after a soft-search check
Run eligibility checks on two or three cards, then apply for only the one most likely to accept you. Every full application adds a hard search to your file.
See the impact before you apply: Our Credit Score Simulator shows how a new card, your balance and on-time payments could change your credit profile over time.
How to Use It So It Actually Builds Credit
Register to vote at your current address on GOV.UK before applying. Lenders use it to confirm who you are.
Set up a full-balance direct debit on day one.
Put one small, regular bill on it, such as your phone or a streaming subscription.
Keep your balance low. Aim to use under 30% of your limit when the statement is produced.
Never withdraw cash. Cash withdrawals are charged interest straight away and usually a fee too.
Don't apply for other credit for at least six months.
Paying only the minimum on a card at 35–40% APR can keep you in debt for years. The regulator has noticed. Under FCA rules, if you pay more in interest and charges than you repay over 18 months, your provider must contact you about paying faster. After 36 months, they must help you clear the balance, which may include reducing or waiving interest. When the FCA first looked into this, customers in persistent debt were paying about £2.50 in interest and charges for every £1 of their balance they repaid.
Credit card borrowing is still rising. Bank of England figures show UK households borrowed a net £0.9 billion on credit cards in July 2026 alone. A credit builder card should shrink your risk, not add to that total.
The Bottom Line
The best credit builder card is the one you're likely to be accepted for and can pay off in full each month. Tesco Foundation has the lowest rate, Barclaycard Forward rewards good behaviour, and Capital One offers the most room to grow. Aqua and Vanquis are there if you've been declined elsewhere. Check eligibility first, apply once, and let a year of on-time payments do the work. Then follow our guide on How to Improve Your Credit Score Fast to keep the momentum going.
Frequently Asked Questions
Will a credit builder card really improve my score?
Yes, if you use it well. On-time payments and low balances are reported every month. Most people see a noticeable change within 6–12 months.
Can I get a credit builder card with a CCJ or default?
Often, yes. Aqua and Vanquis specialise in applicants with poor history. Use their soft-search eligibility checkers to see your chances before you apply.
When should I switch to a better card?
After 12–18 months of on-time payments, check your eligibility for mainstream cards. Keep your builder card open if it has no fee, because its history helps your file.
Does checking eligibility affect my credit score?
No. Eligibility checkers use a soft search, which only you can see.
What credit limit will I get?
Usually between £200 and £1,500 to start. You may be given more or less, depending on your circumstances.
This article is for informational and educational purposes only and does not constitute financial advice. Rates, limits and features were taken from providers' websites in September 2026 and may change. Always check the provider's current terms before applying.
Still with us?
Take the community poll, test yourself with the quiz — or both.
Topic hubs
Browse more articles in these categories and tags.
Maya Thornton is a personal finance writer specializing in credit, debt strategy, and consumer banking. With a background in financial counseling, she translates complex credit system mechanics into plain-language guides that help everyday people take real control of their financial lives.
125K followers89 articles
Related reading
Related articles
Closely related by shared tags and categories — continue in this topic cluster.